 Image Description: On The Record 09-22-26. Fake $40T Debt Bomb. Another Bessent Fail. Alex Karp Is Nuts, 750K Cut from Obamacare. + Elephant Graveyard. UNFTR.
Stupid Math
We’re going to pivot to more political brushfires heading into the midterms, but I wanted to put an endcap on our macroeconomic discussions from the summer. Let’s talk about our debt. I realized recently that I never really put structure to the argument that the size of the national debt isn’t really the issue people think it is; it’s the way we politicize it. It’s a logical bridge due to the weaponization of the number and our misunderstanding of the role debt plays in domestic affairs and geopolitics.
To be clear, it’s a really big fucking number. Forty trillion dollars.
Both sides of the aisle use it as a cudgel to rail against entitlement programs or military spending or to stake their position on taxation. Should we take more from wealthy people, poor people, states, the military, foreign countries? That’s the sum total of the discussion surrounding debt. All roads lead to what has to go in order to rein it in.
Before we ask what to cut, let’s ask a more basic question:
Who owns the other side of that debt?
Gross federal debt sits somewhere around $40 trillion dollars: roughly $8 trillion owed to government accounts, including trust funds, and $32 trillion held by “the public.”
“The public” does not mean Americans. It includes domestic investors, foreigners, and the Federal Reserve. Foreigners hold about $9.25 trillion; the Fed holds roughly $4.5 trillion.
That leaves $18 trillion or so with other domestic holders, plus those government accounts. As a caveat, there are issues with some of this math, which I’ll address, but on balance this is a rounded map of debt ownership.
Okay, so who are these foreigners?
To follow the foreigners, the Treasury publishes Treasury International Capital (TIC) data. UNFTR is one of the few places to periodically report on TIC data because it helps us evaluate trends in capital movement. TIC tracks cross-border securities transactions and banking flows, separating private investors from official institutions, including central banks and governments. Think of it as a financial traffic report.
And the traffic is changing. Over the 12 months through July, recorded foreign Treasury acquisition fell from about $700 billion dollars to about $300 billion: nearly $400 billion less additional buying, not $400 billion of liquidation. That’s an important note. We never go backwards because we’re always issuing net new debt into the world to cover our expanding deficits. But what this shows is a slowdown in the volume of purchases from foreign entities during a rather significant period of debt growth.
Foreigners remained net buyers over that period, but added much less. Meanwhile, foreign net purchases of American equities increased. “America” is not one investment.
Who absorbs the supply?
Over the year through June, domestic sectors excluding the Fed absorbed about three-quarters of net Treasury issuance, with the Fed and foreigners accounting for the remainder. Money market funds, mutual funds, banks, pensions, and households all participate.
Notice the word “net.” If an investor replaces a $100 Treasury bill when it matures, that’s another purchase, but not another $100 of savings. Rolling over the same debt doesn’t manufacture new net demand.
But there is a messy offshore footnote we’ve reported on before. Fed researchers estimated that Cayman-domiciled hedge-fund Treasury holdings were undercounted by about $1.4 trillion at the end of 2024. Missing holdings can wind up in the statistical remainder labeled “households”; a September Fed paper still works around that problem.
The debt hasn’t disappeared. But we should be careful about claiming we know exactly who holds it.
Think Differently About Debt
Now step back. A Treasury security is a government liability and its owner’s asset; interest paid by the government is income to whoever holds it. That is the half of the balance sheet the debt clock leaves out.
Suppose the government spends $100 and collects $90 in taxes. Its $10 deficit is also a net addition to everybody else’s financial claims on government, including foreign holders. The political question is whose.
None of that tells us whether the money was used well. Did it build something? Retire debt elsewhere? Get pocketed or invested? Impossible to really know. But the deficit isn’t money that vanished. Someone received the spending, and someone holds the financial claim.
“We owe it to ourselves” doesn’t absolve us of the debt conversation. We are not one giant household with one bank account. Ask who receives the payments, who pays the taxes, and who loses services.
Debt issuance also isn’t the same thing as printing money. Banks create deposit money through lending; Treasury makes payments from an account funded by taxes, borrowing, and other receipts.
This is why your household budget is different from the federal government’s. You can’t tax. You can’t print money. You can’t run continuous deficits, unless you’re the Trump household throughout the ‘80s, ‘90s, and most of the 2000s. More importantly to our political discussion, financial capacity isn’t productive capacity. A real debt conversation asks what spending builds, what the economy can supply, and who benefits.
Take the Fed and the Treasury debt it already owns.
What if the Fed forgave Treasury’s obligation?
No retiree’s bond would be confiscated. The original seller was paid when the Fed bought it. This is one public institution canceling a claim on another, not the government refusing to honor your savings. This is famously where libertarians and modern monetary theorists are on the same page.
There are legal and operating arrangements to resolve. Canceling the bond would not erase bank reserves or automatically end the interest the Fed pays on them. It could lower the Treasury debt tally without eliminating those outside claims. But that’s different from saying somebody’s retirement account has to take a haircut. If you’re telling me the public gets hurt, show me whose payment disappears and why.
Financial repression is another possibility, but it’s uglier. Financing debt below the level of inflation erodes what creditors—real people and savers—receive in real terms. That actually costs savers purchasing power. By the way, outside of the fact that Donald Trump and people like him are the ones who benefit most from lowering the federal funds rate, it’s also a tactic that would help to reduce the outstanding debt. It’s shitty, but it’s a real thing.
Rather than having imaginative conversations, Washington keeps returning to the same question: What do we raise, and what do we cut? I think the fixation on a balanced budget misses the point, but we’ll play the game for now.
If we spend X and take in Y, balancing the budget means changing one or both. The arithmetic isn’t the problem. It takes this idea that the outstanding balance is objectively a bad thing at face value rather than asking whether the money is being put to good and productive use. This is where the politics live: Who gets hurt, who gets ahead, and which choices never even make the list?
In June, Mike Johnson said Medicare, Medicaid, and Social Security had to be “adjusted and fixed”; he subsequently denied that Republicans intended to reduce benefits. But set the denial beside the legislation. The Congressional Budget Office projects that the 2025 reconciliation law reduces resources toward the bottom while increasing them further up, including through lower Medicaid and food-assistance spending.
Why not increase the corporate tax rate? Why not ask more of the fucking billionaires before asking retirees and the poorest among us to live on less?
The focus on balancing the budget shifts the lens. People think about what can be cut rather than built. Can’t touch the military budget because the idiot in charge might start a war. Can’t tax corporations because they might stop being so corporatey or whatever the fuck they say when we talk about taxing profits.
So the conversation turns to entitlements. They’ve worked for decades to make it seem as though we’re entitled, not entitled to these things.
It’s an inversion of what “mandatory” should mean politically. The obligations to people who worked, paid in, got sick, or grew old become discretionary. The preferred tax treatment and the next military allocation become mandatory if not sacrosanct. We talk about mandatory versus discretionary in the budget conversation but in practical terms let’s explore this. If we always fund the military at levels beyond what it requests—year after year, decade after decade—does it really matter if it’s technically “discretionary”? Because it sure seems mandatory to me.
Now, I’m not arguing that every deficit is good. I’m arguing that “we can’t afford it” isn’t an answer until somebody explains what “it” is and who benefits.
Which brings me back to Trump. The dollar’s international role rests on deep markets, economic strength, and trust in American institutions and the rule of law. The debt clock cannot measure that trust.
My warning is about squandering it. A gradual erosion of dollar demand is possible without China simply taking America’s place. Neither the successor nor the timetable is predetermined.
You have to appreciate the magnitude of the gift these people inherited to understand the scale of the malpractice. This is the easiest economy to not fuck up.
If Washington wants to revisit its own internal obligations, let’s have that conversation. If it wants more revenue, I’ll choose asking more of multinational corporations before cutting grandma and grandpa’s benefits. Those are different tools, but neither requires treating ordinary people as the first place to look for savings.
We don’t need to pretend the debt is meaningless. We need to stop pretending its size tells us whose claims to honor, whose taxes to raise, and whose future to cut. That’s a political choice. And I’ll choose fewer missiles before I choose fewer meals.
Or, we just stop focusing on that big hairy number that amounts to little more than a balance sheet entry and start focusing on rebuilding our credibility and a government that works on behalf of its people.
And I’ll Throw in Our Dog
Nearly half of homebuyers are getting something extra from the seller. In the three months ending in August, 44.7% of sales included concessions, up from 42.6% a year earlier and the highest share for that period since Redfin’s records began in 2020. These are things like closing-cost assistance, repair credits and mortgage-rate buydowns, not reductions in the sale price.
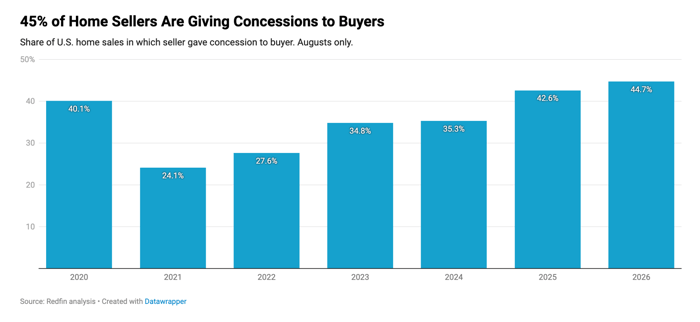
Sources: Redfin
The regional differences are enormous. Sellers offered concessions in roughly 73% of Atlanta sales, 68% in Charlotte and 67% in Phoenix, compared with just 4% in San Jose and 6% in New York. Redfin connects the Sun Belt’s greater negotiating room to pandemic-era construction and cooling demand.
This is the stage before total demand destruction and an absolute decline in housing. The housing market can soften without that weakness showing up entirely in headline prices. A seller who helps cover your closing costs or buys down your mortgage rate is effectively making the purchase cheaper without necessarily lowering the recorded sale price. That’s growing leverage for buyers, but it isn’t the same thing as housing suddenly becoming affordable.
What makes housing interesting is that a disturbing sign of economic decline can also be a positive step toward affordability. We’ve talked about this before: How elevated home values give retirees and older homeowners a false sense of security that they have a protected asset that continually appreciates. This kind of asset appreciation has worked out well for some in the boomer generation but has prohibited millennials from fully entering the housing market. So if prices begin to come down, it makes homeownership more attainable but threatens the nest eggs of the largest retirement-age cohort this country has ever had.
 Max
Max is a political commentator and essayist who focuses on the intersection of American socioeconomic theory and politics in the modern era. He is the publisher of UNFTR Media and host of the popular Unf*cking the Republic® podcast and YouTube channel. Prior to founding UNFTR, Max spent fifteen years as a publisher and columnist in the alternative newsweekly industry and a decade in terrestrial radio. Max is also a regular contributor to the MeidasTouch Network where he covers the U.S. economy.